
Monthly Investment Outlook - September 2026
What’s shaping markets this September? The JioBlackRock Investment Team shares its monthly investment outlook for September 2026, explaining recent market sentiments and how portfolios are being positioned today. Explore our latest market views and asset allocation insights.
JioBlackRock advantage
·
Published on 15 September 2026
·
5 min read
Market Review
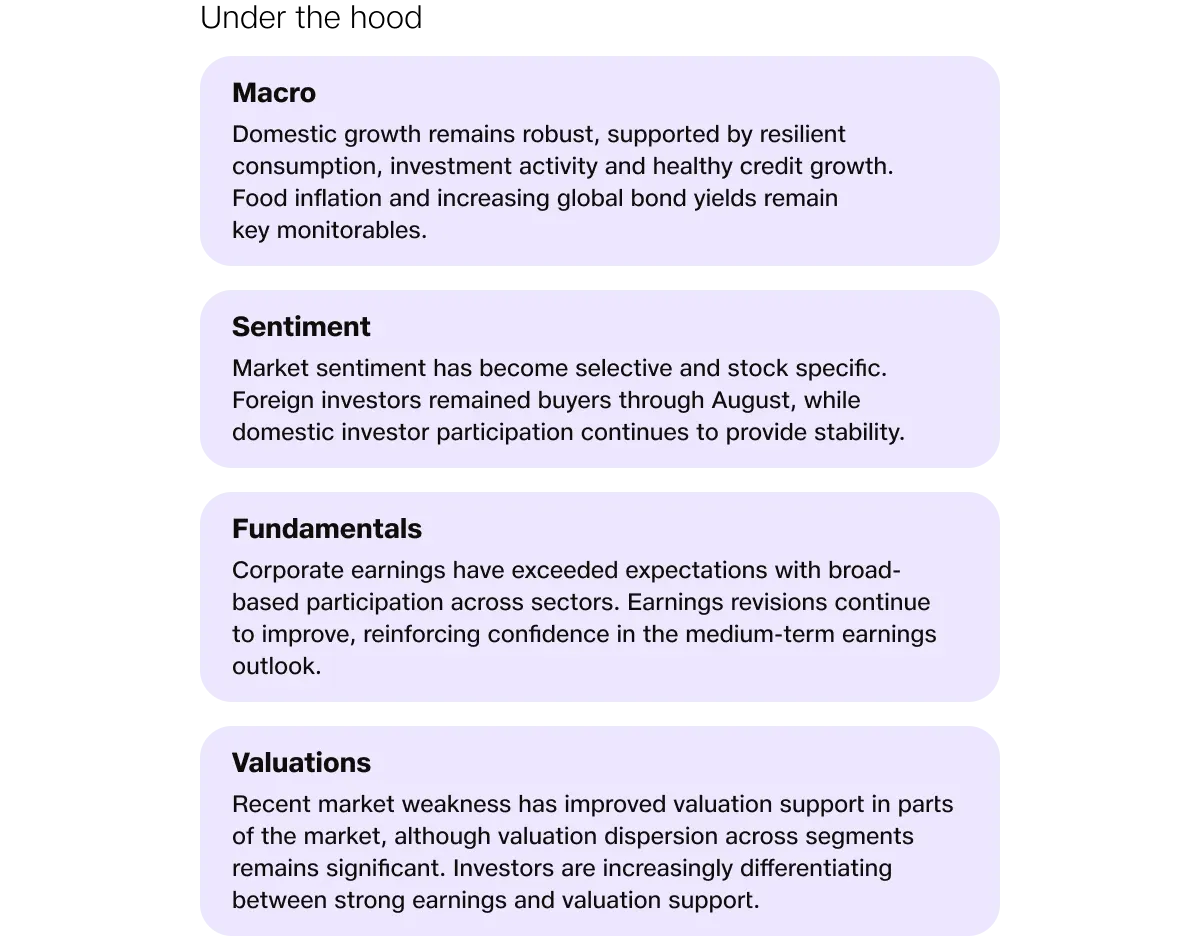
In fixed income markets, Indian government bond yields moved higher over the past month, with the benchmark 10-year government bond yield rising from around 6.7% to 7.0%. Higher crude oil prices and rising global bond yields weighed on domestic bond markets despite ample liquidity in the banking system.
India’s Q1 FY27 GDP came in strong despite a period of exogenous commodity and currency stress. Real GDP expanded by 7.8% YoY, above the RBI’s 7.0% projection and market expectations of approximately 7.1%. Growth was led by services, which expanded 10%, alongside stronger manufacturing and resilient investment activity. The recently concluded Q1 FY27 earnings season reinforced this resilience. Earnings growth exceeded expectations across a broad range of sectors, with financials, industrials and consumer-linked businesses delivering particularly strong results. Earnings revisions have continued to improve and should support medium-term corporate profit outlook.
Inflation continued to inch higher, with July CPI inflation rising to 4.5%, marking the ninth consecutive monthly increase. Food prices were the main contributor with a 5.2% increase. Core inflation increased by 3.9% but remains within the tolerance range of the RBI. Although inflation remained manageable, markets have started to focus on the trajectory of food prices due to deficient monsoon season as well as input cost pass-through.
Domestic investor participation remained supportive with continued increase in monthly SIPs. Foreign portfolio investors remained net buyers of Indian equities for the second straight month.
Market Performance
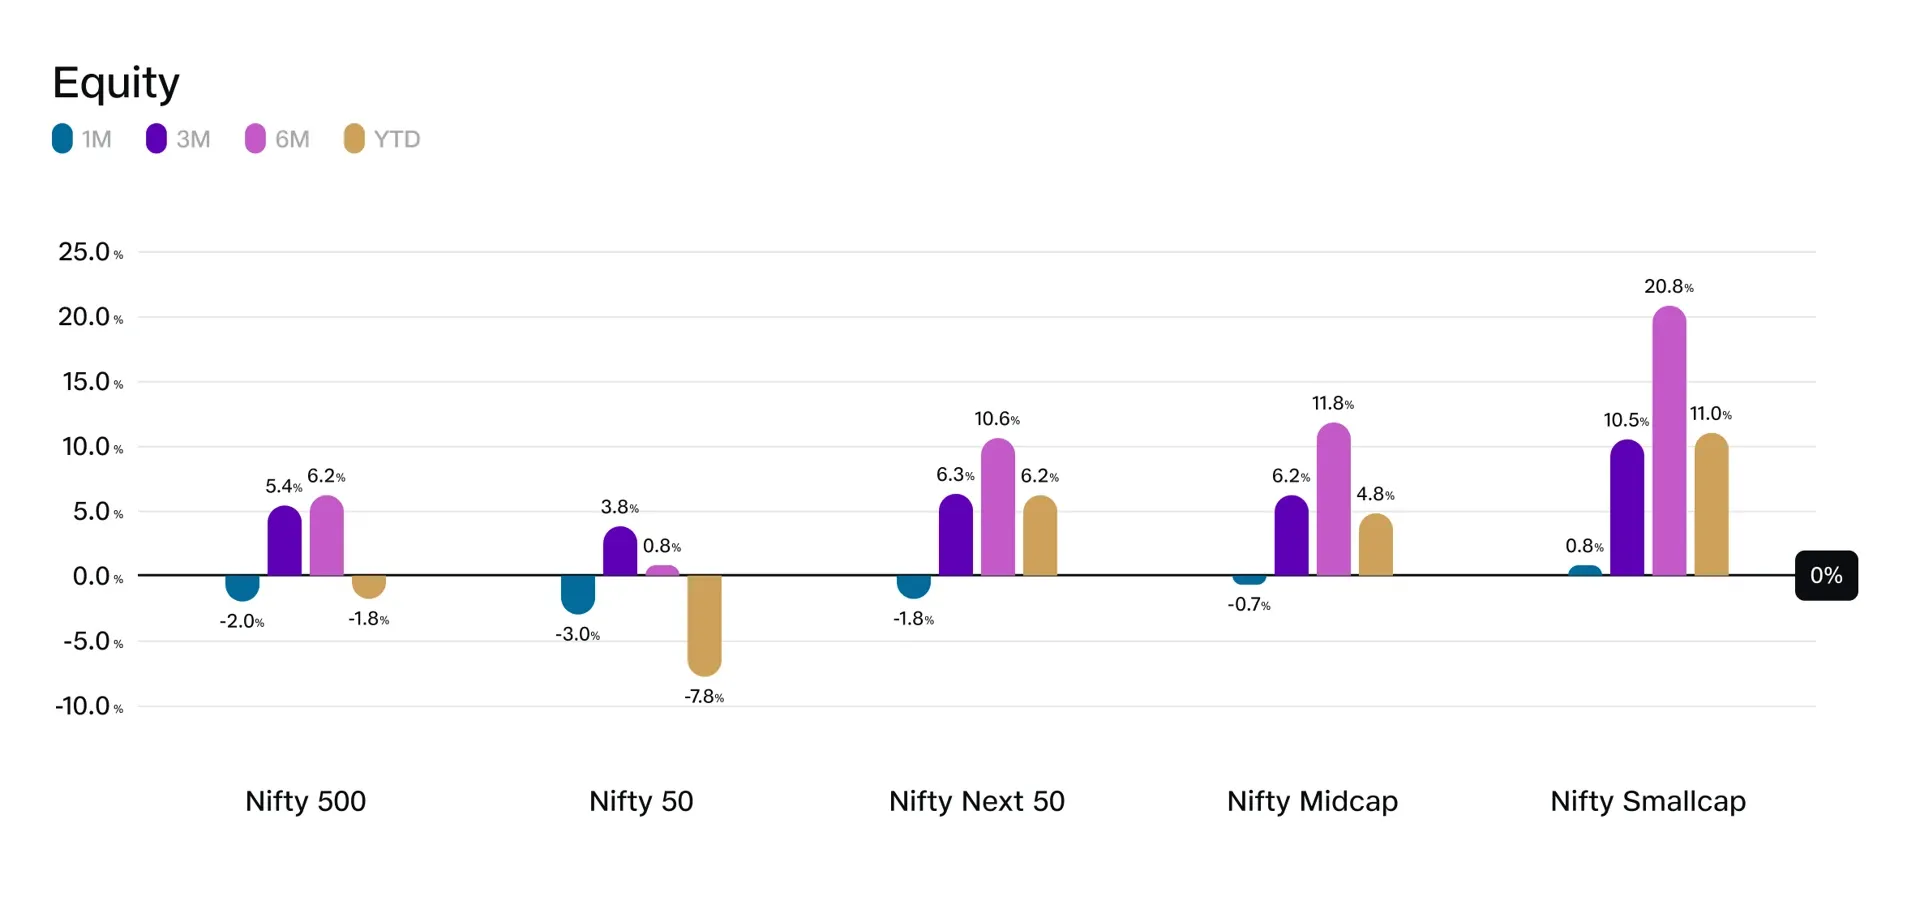
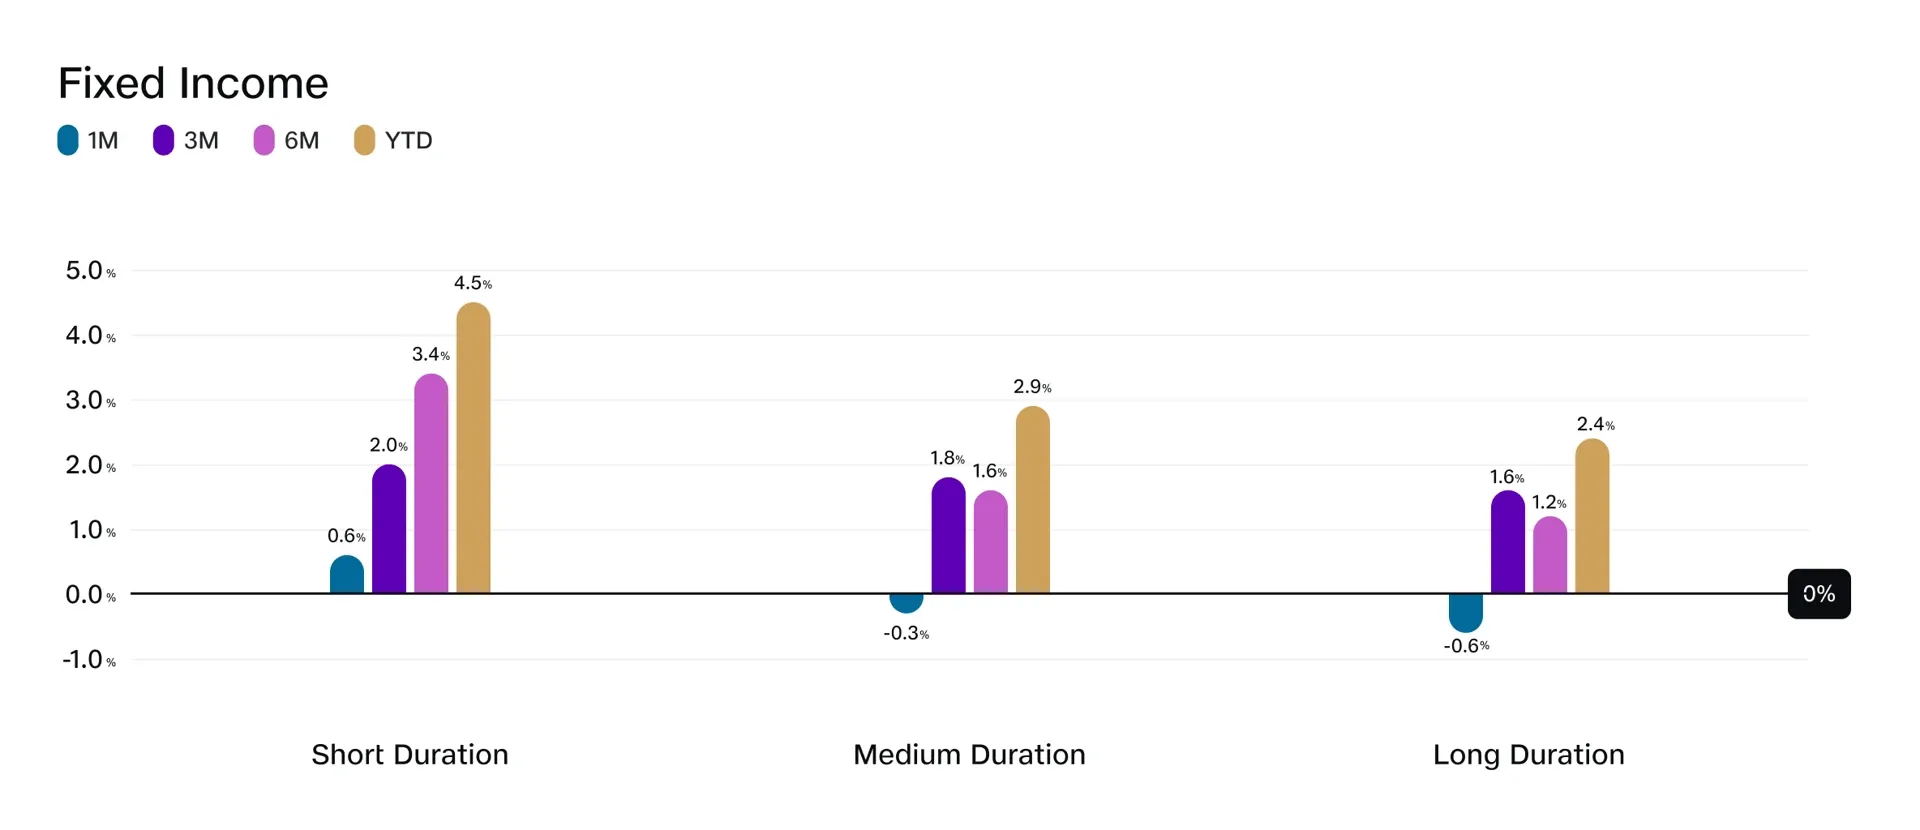
Source: Bloomberg,
Data: As of 4th September 2026
Asset Allocation View
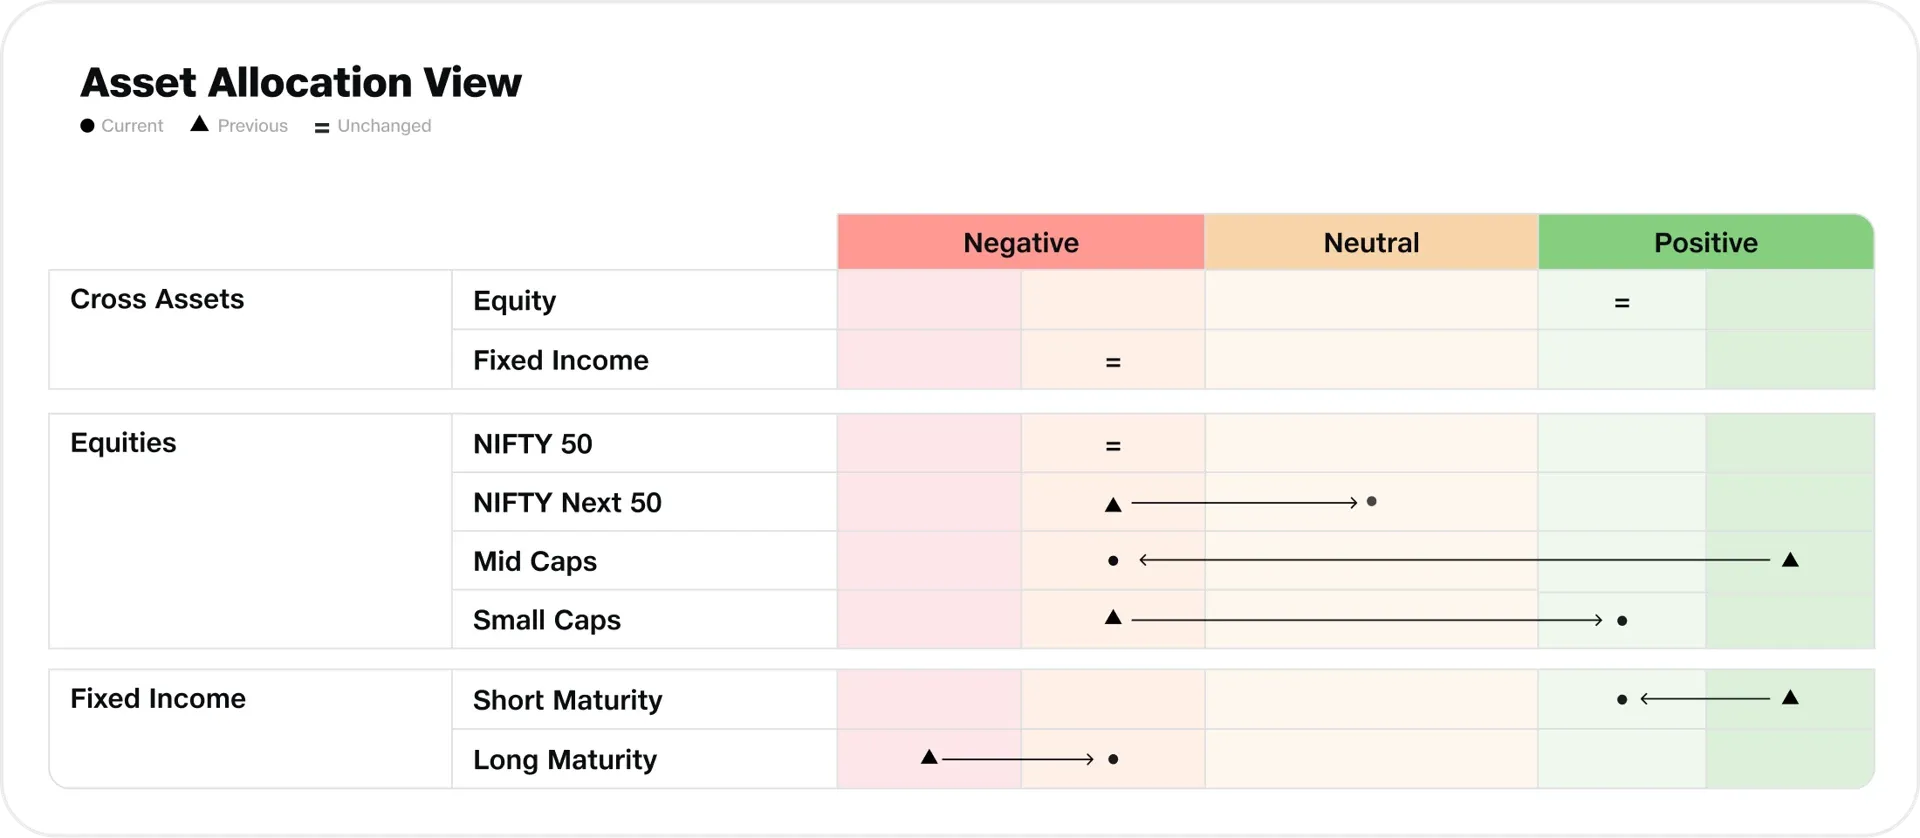
We remain constructive on Indian equities with preference for equities over fixed income in asset allocation. The pullback over the past month was on account of elevated equity valuations, rising global bond yields and higher crude oil prices rather than any deterioration in domestic fundamentals. Corporate earnings have exceeded expectations, GDP growth surprised positively at 7.8%, and foreign investors remained buyers of Indian equities through August. While geopolitical developments, energy prices and global interest rates continue to warrant monitoring, this has not altered our positive medium-term outlook for equities.
Within equities, our market-cap preference has changed from mid-caps towards small-caps. The recently concluded earnings season demonstrated broad-based strength across corporate India, with smaller companies continuing to benefit from improving profit margins and stronger earnings momentum. In contrast, mid-caps have outperformed for an extended period, and their relative valuation support has reduced. Large-cap fundamentals remain healthy, although earnings growth remains more moderate.
Within fixed income, our preference for shorter-maturity investments continues. As uncertainty around inflation, global interest rates and crude oil prices remains, shorter-maturity fixed income securities continue to offer an attractive balance between income generation and capital stability. However, we have reduced the extent of our preference for shorter duration fixed income since the longer maturity government bonds have started to provide some value around current levels.
Thank you for reading our September 2026 Investment Outlook. We look forward to sharing our latest market perspectives with you again next month.
Disclaimers
This Commentary is for limited distribution only and the recipient shall not copy/circulate/reproduce/quote contents of this document, in part or in whole, or in any other manner without prior and explicit approval of JBIAPL and treat the information contained in this Commentary with utmost confidentiality. The information is only for consumption by the client/recipient and such material should not be redistributed. If you are not the intended recipient, you are hereby notified that any use, distribution, reproduction, or any action taken or omitted to be taken in reliance of the same is strictly prohibited and may be unlawful.
This Commentary contains information, data, charts, and materials obtained from external and third-party sources ("Third-Party Information"). While JBIAPL believes such Third-Party Information to be reliable, JBIAPL has not independently verified such information and makes no representation or warranty as to its accuracy, completeness, or timeliness. JBIAPL assumes no liability for any errors, omissions, or inaccuracies in such Third-Party Information.
This Commentary is provided "as is" for informational and discussion purposes only. JBIAPL makes no representation or warranties, express or implied, regarding:
- The accuracy, completeness, or reliability of the information contained herein;
- The profile or data points of any underlying issuers, products or services;
- The suitability of any information for any particular purpose;
- Any outcomes or results that may be achieved.
Nothing in this Commentary constitutes legal, financial, investment, tax, professional advice or an investment advice, research report, or a recommendation or a solicitation to invest in any financial product or security or entity, or a promotion of any such financial product or security or entity, in any manner whatsoever or recommendation by JBIAPL of an investment strategy or whether or not to "buy", "sell" or "hold" an investment. The information available in this Commentary should not be considered as sufficient upon which to base an investment decision and is not based on consideration of the recipient's individual circumstances. Recipients should consult their own advisors before making any decisions based on information contained herein. This Commentary contains certain assumptions and views, which JBIAPL considers reasonable at this point in time, and which are subject to change. The views set out in this Commentary are indicative and are based on current market prices and general market sentiment.
All intellectual property rights in this Commentary, including but not limited to copyrights, trademarks, trade secrets, and proprietary information, remain the exclusive property of the JBIAPL or its licensors. No license or right is granted except as expressly stated herein.
To the fullest extent permitted by law, JBIAPL shall not be liable for any damages, losses, costs, or expenses arising from or relating to the use of, reliance upon, or inability to use the information contained in this Commentary.
Blogs
We want everyone to feel confident about investing and our learning hub is a good place to start – wherever you are on your journey.
Monthly Investment Outlook - August 2026
What’s shaping markets this August? The JioBlackRock Investment Team shares its monthly investment outlook for August 2026, explaining recent market sentiments and how portfolios are being positioned today. Explore our latest market views and asset allocation insights.
Monthly Investment Outlook - July 2026
What’s shaping markets this July? The JioBlackRock Investment Team shares its monthly investment outlook for July 2026, explaining recent market sentiments and how portfolios are being positioned today. Explore our latest market views and asset allocation insights.
Monthly Investment Outlook - June 2026
What’s shaping markets this June? The JioBlackRock Investment Team shares its monthly investment outlook for June 2026, discussing the recent market pullback, the impact of geopolitical developments and oil prices on investor sentiment, and our latest asset allocation views. Explore our perspectives on markets, the economy, and opportunities across equities and fixed income.
Why is asset allocation important during periods of market stress?
Equities fuel growth, fixed income provides stability, and gold offers downside protection in uncertain times. Each asset class performs differently under varying market conditions, so what does this mean for you? Read to know….
Buy and Hold vs Rebalancing - What is better?
When it comes to building long-term wealth, investors often fall into two camps: those who prefer to buy and hold, and those who favour periodic rebalancing. The first strategy relies on patience and simplicity, the other on discipline and adaptability.
How to interpret returns: Making sense of investment numbers for you
In this article we’ll break down the most common types of investment returns in simple language. By the end, you’ll know exactly what the numbers mean and how to use them.
